All Categories
Featured

Table of Contents
Available Growth OptionsUnderlying Cost StructureParticipating Loan RatesCompany Credibility (given that much of the above won't be ensured)Since IUL cap rates, participation rates, and loan rates have actually been a moving target changing hugely, we did not wish to post actual numbers only to have them become outdated a month or more later on.
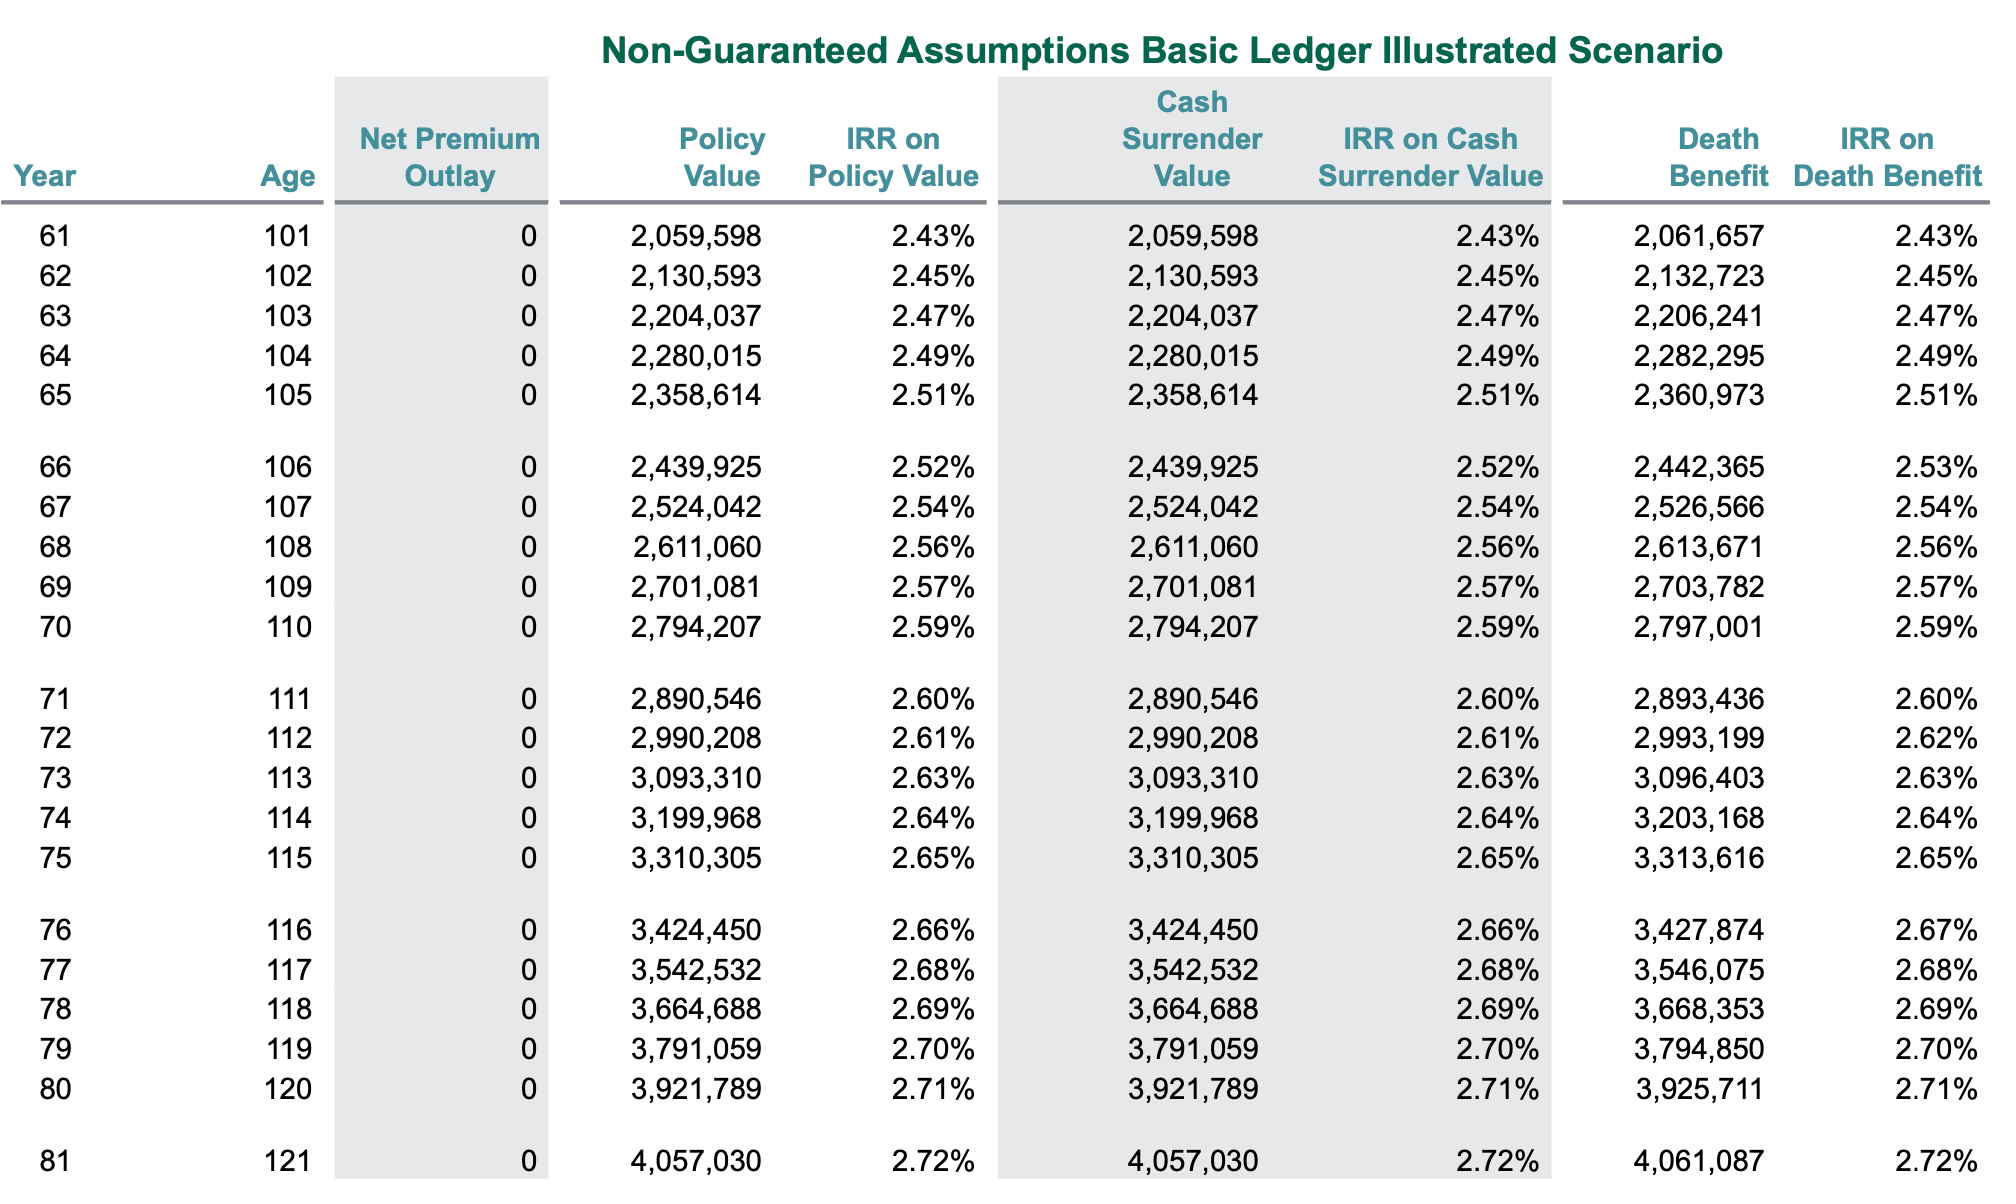
Indexed Universal Life policies involve fees, caps, involvement rates, spreads, policy charges, and loan danger. Policy loans and withdrawals may decrease cash value and death benefit, may cause the policy to lapse, and may develop taxable earnings if not managed effectively.
Upgraded September 13, 2026Searching for the "best IUL companies" or the "finest IUL policies for cash build-up" in 2025? You're not alone. Indexed Universal Life (IUL) insurance has gained significant attention as a financial tool that combines a survivor benefit with the potential for money worth growth connected to market indexes, frequently pitched as a part of a retirement method.
Best IUL Plans for Retirement
The perfect policy and business depend entirely on your special monetary objectives, risk tolerance, health, and timeline. Understanding IUL requires browsing a landscape of caps, floors, involvement rates, fees, and complicated illustrations.
We're an independent insurance agency established by a former very first responder and military spouse, and staffed by specialists with backgrounds rooted in public service. Our mission isn't just to offer insurance coverage; it's to serve and inform our clients, helping them browse complicated monetary products like IUL.
This independence enables us to objectively go shopping the marketplace, compare the finest IUL items available, and tailor protection particularly to your private requirements and objectives. Our company believe in finding the best fit for you, not pressing a one-size-fits-all solution. Our universal life insurance guide discusses the more comprehensive alternatives in this classification.

Financial Options for Veterans
At its core, Indexed Universal Life is a kind of long-term life insurance coverage policy. Unlike term insurance coverage, which covers you for a specific duration, long-term policies like IUL are created to last your entire lifetime, provided premiums are paid and the policy remains in force. IUL policies have several key parts: This is the primary function of any life insurance coverage policy.
IUL offers versatility in death benefit quantities, which can often be adjusted over time. This is the specifying feature of IUL.
You are not straight investing in the index itself. Insurance coverage business utilize numerous methods to calculate the interest based on index performance.
Evaluating Medicare Supplement Plans
Some policies use 100% or even higher participation rates, however this often features other trade-offs. A lot of IUL policies have a cap, which is the optimum rate of interest that can be credited to your money worth in an offered duration, regardless of how high the chosen index performs. If the index gains 15%, the involvement rate is 100%, but the cap is 9%, your cash value would be credited with 9% interest (before fees).
Insurance in Perris CADiscovering the very best IUL carrier typically involves comparing current and historical cap rates, however this is just one piece of the puzzle. This is a vital protective feature of IUL. The floor is the minimum interest rate your policy can make, even if the connected index experiences losses. A lot of frequently, the floor is 0%.
Like other universal life policies, IUL offers versatility in premium payments. It's immediately clear that the interaction in between these factors develops significant variation among the IUL policies provided by various business.
An independent company like Insurance By Heroes is important for comparing these detailed information throughout numerous top IUL providers. The search keywords "best IUL for money accumulation" and "finest IUL for retirement" highlight this typical interest.

Latest Posts
Direct Advice for Life Insurance Purchasing
Current Level Term Rates in the US
Comparing Term and Whole Life Insurance Advice